What Kevin Plank's entrepreneurial journey teaches business owners about credit, financing, and building something from the ground up.
Today, Under Armour is one of the most recognizable athletic apparel brands in the world. Its products are worn by professional athletes, college teams, and everyday fitness enthusiasts.
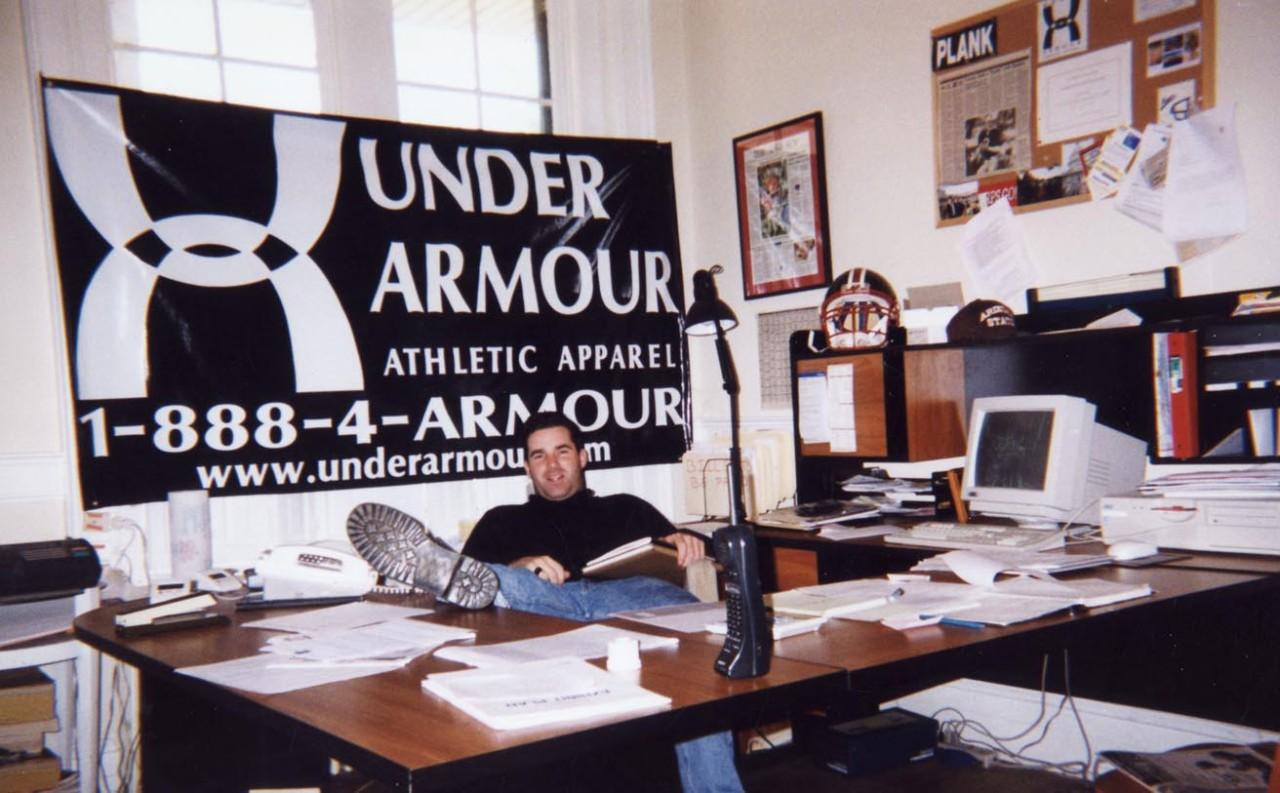
But long before Under Armour became a household name, its founder was a young entrepreneur with an idea, limited resources, and a growing pile of credit card debt.
Kevin Plank's story is a fascinating example of how entrepreneurs sometimes use personal credit to help get a business off the ground.
It's also a reminder that access to capital can create opportunities, but borrowing money comes with real risks.
It All Started With a Simple Idea
In 1996, Kevin Plank was a former University of Maryland football player who had grown frustrated with the cotton T-shirts he wore underneath his football equipment.
During practices and games, those shirts would become soaked with sweat, making them heavy and uncomfortable.
Plank believed there had to be a better solution.
He began developing a lightweight, moisture-wicking athletic shirt designed to keep athletes more comfortable during physical activity.
That idea eventually became Under Armour.
Like many entrepreneurs, however, Plank faced a significant challenge.
He needed money to turn his idea into an actual business.
Five Credit Cards and a Dream
Plank initially used personal savings to help launch Under Armour. As the company developed, he also relied heavily on credit cards to cover business expenses.
According to published accounts of Under Armour's early years, Plank accumulated approximately $40,000 in credit card debt across five cards.
Think about that for a moment.
Before Under Armour became a major athletic apparel company, its founder was using credit cards to help finance the business.
Those funds helped support the company's early operations as Plank worked to manufacture products, generate sales, and establish relationships with customers.
Of course, there was considerable risk involved.
Credit cards can carry high interest rates, and borrowing without sufficient revenue to support repayment can create serious financial problems.
Plank was betting on his ability to turn a promising product into a sustainable business.
There was no guarantee that bet would pay off.
How Credit Cards Helped Bridge the Gap
One of the biggest challenges entrepreneurs face is accessing financing before their businesses have established financial histories.
Traditional business loans may require operating history, consistent revenue, financial documentation, or other qualifications that a new business simply doesn't have yet.
Credit cards can sometimes provide an alternative source of purchasing power.
Depending on the issuer and product, applicants may qualify based on factors such as personal credit history, income, existing obligations, and business information.
This can make credit cards worth evaluating for certain early-stage business expenses.
In Plank's case, using multiple credit cards helped him access capital during Under Armour's formative years.
Today, the practice of strategically using multiple credit cards to increase available purchasing power is often referred to as credit card stacking.
Although Plank's experience involved multiple cards, it should not be assumed that he used the same strategies, products, or promotional offers available to entrepreneurs today.
The underlying concept, however, remains relevant: different financing tools may help businesses address different capital needs.
From Credit Cards to Additional Financing Opportunities
As Under Armour began establishing itself, the company's financing needs evolved.
The business was no longer just an idea. It was developing products, attracting customers, and working to expand.
That growth created new financial demands.
According to accounts of the company's history, Under Armour eventually obtained additional financing, including a small-business loan in 1998.
This illustrates an important principle of business financing.
The financing that helps launch a company may not be the same financing that supports its next stage of growth.
A startup might initially rely on personal savings or credit cards.
As it establishes revenue, operating history, and stronger financial records, it may become eligible for other financing products.
These could include business lines of credit, term loans, or other commercial financing options.
Eligibility is never automatic, and taking on credit card debt does not guarantee access to future financing.
However, understanding how financing options differ can help entrepreneurs make more informed decisions as their businesses evolve.
What Business Owners Can Learn From Under Armour
Kevin Plank's experience offers several lessons for entrepreneurs considering how to finance their businesses.
1. Access to Capital Can Create Opportunities
Having an idea is one thing. Having the resources to execute it is another.
Business owners often need capital for inventory, equipment, marketing, staffing, or other operational expenses.
Understanding available financing options can help entrepreneurs evaluate how to support those needs.
2. Personal Credit Can Matter, Even for Business Financing
Many entrepreneurs assume they need years of business revenue before they can explore financing.
While some lenders do require established revenue and operating history, other products may consider an applicant's personal credit profile.
Credit history, utilization, income, existing debt, and other underwriting factors can influence eligibility.
For that reason, maintaining healthy personal credit can be valuable for entrepreneurs, particularly during the early stages of business ownership.
3. Multiple Credit Cards Require Careful Management
Using multiple credit cards can increase total available credit, but it also introduces additional financial obligations.
Each account may have different interest rates, fees, payment dates, and terms.
Opening multiple accounts can also affect personal credit through inquiries, new accounts, and changes in overall credit utilization.
Business owners should consider their ability to manage and repay every account rather than focusing exclusively on the total amount of available credit.
4. Financing Should Evolve With Your Business
A financing solution that makes sense during startup may not be appropriate several years later.
For example, credit cards may be useful for certain purchases or shorter-term expenses, while a term loan may be more appropriate for an investment requiring predictable payments over a longer period.
Business lines of credit may offer flexibility for eligible businesses with recurring working capital needs.
The right financing structure depends on the company's financial condition, intended use of funds, repayment capacity, and available terms.
5. Borrowing Money Is Not a Business Strategy by Itself
Perhaps the most important lesson from Under Armour's story is that financing was only one part of the equation.
Plank also had a product, a market opportunity, and the determination to build customer relationships.
Access to credit helped support his efforts, but it did not eliminate the challenges of building a successful company.
Borrowing should support a thoughtful business plan, not replace one.
Could Credit Card Stacking Make Sense for Your Business?
Credit card stacking generally refers to obtaining multiple credit cards to increase the total credit available to an individual or business.
Some business owners explore this approach to help cover eligible business expenses or support working capital needs.
Certain business credit cards may offer introductory 0% APR periods on qualifying purchases or balance transfers, depending on the issuer's terms.
However, these offers are temporary, may involve fees, and typically transition to a standard APR after the promotional period ends. Not all transactions qualify for promotional rates.
Additionally, approval for one credit card does not guarantee approval for another, and applying for several accounts can affect your credit profile.
Before pursuing multiple cards, business owners should evaluate their anticipated expenses, repayment timeline, borrowing costs, and ability to manage multiple accounts responsibly.
Credit card stacking is not appropriate for every business.
Explore Your Business Financing Options With 7 Figures Funding
At 7 Figures Funding, we believe business owners should understand their financing options before making important financial decisions.
Whether you're launching a new company, expanding an existing business, or evaluating additional working capital, understanding the differences between financing products is an important first step.
Our team helps business owners explore available financing options, including business credit cards, business lines of credit, and term loans, based on their individual circumstances and applicable lender requirements.
Under Armour's story is an extraordinary example of entrepreneurship, but every business has a different financial situation and path to growth.
Ready to explore your business financing options?
Connect with 7 Figures Funding to learn more about potential solutions for your business.
Sources: Inc., "How I Did It: Kevin Plank"; Forbes coverage of Kevin Plank and Under Armour's early financing history.
Disclaimer: This article is provided for general educational purposes only and does not constitute financial, legal, or credit advice. Historical examples are not representative of typical financing outcomes. 7 Figures Funding is not affiliated with or endorsed by Under Armour or Kevin Plank. 7 Figures Funding assists businesses in exploring financing options offered by third-party lenders and card issuers. All financing is subject to eligibility, underwriting, applicable terms, and lender approval. Rates, fees, repayment terms, and available products vary. No approval, financing amount, promotional rate, or future financing opportunity is guaranteed. Financing discussed is intended for legitimate business purposes.
7 Figures is not a lender. We provide education, guidance, and access to funding resources. Approval and funding outcomes vary by lender and individual credit profile.